
Search by title, topic or phrase
Use our Crypto Search Engine 🔍 to find the topics and keywords you're looking for.
Crypto tax rules determine how cryptocurrency transactions are taxed, reported, and documented under the laws of the applicable jurisdiction. This crypto tax guide for 2026 explains cryptocurrency capital gains and losses, digital asset income, cost basis, taxable transactions, tax reporting, and recordkeeping requirements. Whether you buy, sell, exchange, earn, stake, mine, or otherwise dispose of digital assets, your tax obligations depend on your tax residency, the nature of each transaction, and the rules applicable to the relevant tax year.
Table of Contents
ToggleIdentify disposals, sales, exchanges, rewards, mining, staking, and other activities that may create taxable capital gains, losses, or income under local law.
Determine which tax returns, disclosures, information reports, and filing requirements apply to your cryptocurrency transactions and circumstances.
Maintain acquisition dates, cost basis, proceeds, fees, relevant valuations, and wallet or exchange histories to support accurate tax calculations.
Reconcile transactions across wallets and exchanges, investigate missing records, verify tax classifications, and retain supporting documentation.
Official guidance: For US federal tax requirements, consult the IRS Digital Assets guidance. For other countries, consult the relevant national tax authority. This guide covers crypto capital gains, digital asset income, DeFi, NFTs, staking, mining, and cryptocurrency tax reporting where applicable.
Educational information only; not individualized tax, legal, or accounting advice. Cryptocurrency tax treatment varies by jurisdiction and tax year. Verify applicable rules with the relevant tax authority or a qualified professional.
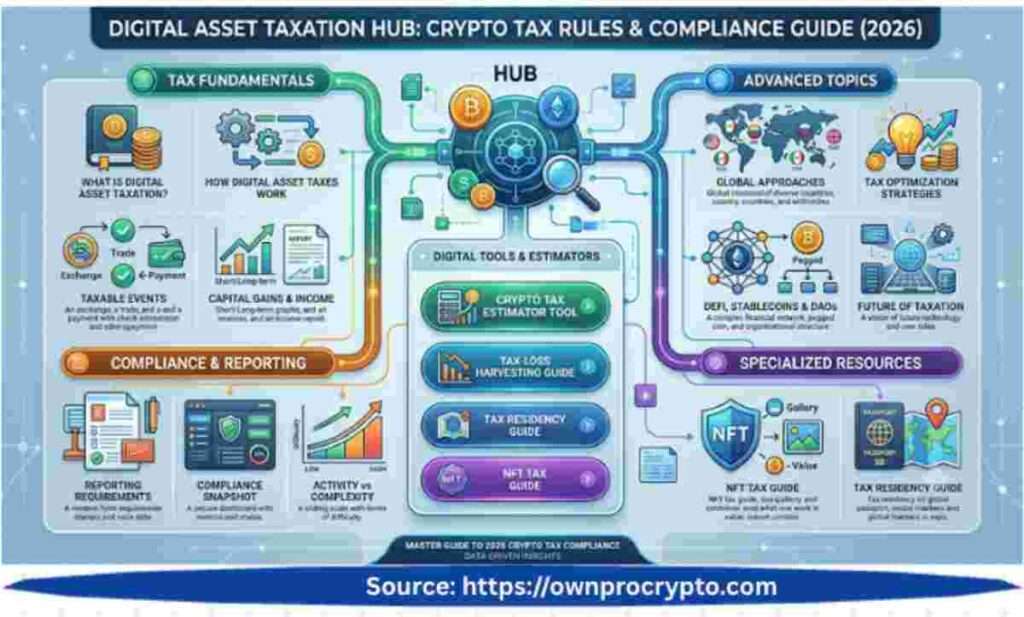
Crypto tax rules can differ according to how a taxpayer acquires, holds, earns, uses, or disposes of cryptocurrency. Individual investors, people conducting a trading business, companies, and recipients of crypto compensation may face different tax treatment and reporting requirements. The correct classification depends on the applicable jurisdiction, the facts of the transaction, and the relevant tax year.
Individuals holding cryptocurrency for personal or investment purposes may need to calculate capital gains or losses when they sell, exchange, spend, or otherwise dispose of assets. They should retain acquisition costs, disposal proceeds, transaction fees, and supporting wallet or exchange records.
People and businesses trading cryptocurrency, accepting digital assets as payment, or conducting other commercial activities must determine the applicable tax classification. Trading frequency alone does not establish business status in every jurisdiction; relevant rules and the surrounding facts must be considered.
Cryptocurrency received as salary, contractor payment, mining proceeds, staking rewards, or other income may be subject to income tax or separate reporting rules. The treatment depends on the activity and local law. A later disposal may create an additional gain or loss.
Businesses, companies, funds, and structures managing assets across multiple entities may need to coordinate tax calculations with accounting records, custody information, valuations, and transaction histories. Applicable obligations depend on the entity, its activities, and the relevant jurisdiction.
Accurate cryptocurrency tax reporting begins with identifying the taxpayer, documenting the transaction, establishing the relevant value and cost basis, and determining the applicable tax treatment. Records should include transaction dates, asset quantities, acquisition and disposal values, fees, wallet transfers, and supporting exchange statements where relevant. Reporting requirements and record-retention periods vary by jurisdiction.
Official guidance: For US federal tax treatment, consult the IRS Digital Assets guidance. For UK tax treatment, consult the HMRC cryptoassets guidance. Readers in other countries should consult their relevant tax authority for current rules.
Crypto capital gains tax calculations generally compare the amount realized on a taxable disposal with the applicable adjusted tax basis of the digital assets disposed of. The result may be a capital gain or loss, depending on the transaction and the governing tax rules. Accurate calculations require reliable acquisition records, disposal proceeds, relevant transaction costs, and the correct method for determining the basis of the units involved.
A simplified crypto capital-gain calculation compares the amount recognized from a disposal with the adjusted tax basis attributable to the digital assets disposed of. However, the treatment of fees, non-cash consideration, basis adjustments, and losses depends on the applicable tax law.
Cost basis is the amount used to determine the tax result when an asset is disposed of. For purchased cryptocurrency, the starting point is generally its acquisition cost, subject to applicable rules and adjustments. Digital assets received as compensation or other income may have a different starting basis based on the relevant tax treatment and valuation at receipt.
Cost-basis tracking becomes more complicated when assets move between exchanges, self-custody wallets, and custodians. A transfer between accounts owned by the same taxpayer may not itself be a taxable disposal, but the transfer should still be recorded so the asset’s acquisition history and basis remain traceable.
Trading commissions, acquisition fees, disposal costs, blockchain network fees, and transfer charges should be recorded separately. Their tax treatment can differ according to the transaction and jurisdiction. Do not assume that every fee can be added to cost basis, deducted from proceeds, or claimed as a separate expense.
When a disposal involves cryptocurrency exchanged for another token, goods, or services, the applicable rules may require a fair-market-value calculation. Preserve the valuation source, date and time, transaction currency, asset quantity, and methodology used. Document the limitations of price data for illiquid or thinly traded assets.
Some jurisdictions distinguish between short-term and long-term capital gains, while others use different classifications. Where holding periods affect tax treatment, preserve acquisition and disposal dates and apply the jurisdiction’s counting rules. Do not assume that the same holding-period thresholds or tax rates apply worldwide.
When the same cryptocurrency is purchased at different prices, the basis assigned to a partial disposal depends on the identification, matching, pooling, or other calculation rules applicable to the taxpayer. Some jurisdictions prescribe specific methods and ordering rules. An exchange’s default tax report should therefore be checked against the relevant legal requirements.
A transfer between wallets or accounts controlled by the same taxpayer may be a non-disposal event under applicable law. Keep the transaction hash, asset quantity, sending and receiving addresses, timestamp, network fee, and evidence of account ownership where available. These records help reconcile exchange histories and preserve the link to the original acquisition.
Suppose an investor purchases one unit of a digital asset for $10,000 and later sells it for $14,000. Assume, solely for this illustration, that an additional $500 in costs is legally includable in adjusted basis.
This example demonstrates the arithmetic only. It does not establish that the additional costs qualify for basis treatment, that no disposal-cost adjustment is required, or that the resulting gain is taxable at a particular rate. Those conclusions depend on the applicable tax rules.
A defensible capital-gain calculation should be traceable to source documentation. Maintain records sufficient to establish the acquisition history, ownership, basis, disposal proceeds, valuation, and adjustments used in the tax calculation.
| Record | Purpose | Examples of Evidence |
|---|---|---|
| Acquisition date and quantity | Establishes the asset’s acquisition history and any applicable holding period. | Trade confirmations, account statements, blockchain records. |
| Acquisition value and basis | Supports the basis calculation under the applicable tax rules. | Purchase records, payment evidence, valuation records. |
| Fees and transaction costs | Allows each cost to be assessed under the correct tax treatment. | Trading statements, network fee records, invoices. |
| Wallet and account history | Helps establish ownership and reconcile asset movements. | Wallet addresses, exchange exports, custody statements. |
| Disposal details | Documents the asset disposed of, the transaction, and the amount realized. | Sale confirmations, swap records, payment documentation. |
| Valuation evidence | Supports values used for disposals or assets received. | Timestamped market prices and documented valuation methods. |
Cost-basis methods, asset identification, pooling, allowable expenses, holding periods, loss recognition, and reporting requirements vary by jurisdiction and tax year. The correct calculation must follow the rules that apply to the taxpayer and transaction rather than a universal cryptocurrency tax formula.
Official guidance: For US federal tax rules, consult the IRS Digital Assets guidance. For UK capital gains rules, consult the HMRC guidance on selling cryptoassets. Other taxpayers should consult the relevant national tax authority.
Educational information only, not individualized tax, legal, or accounting advice. Confirm current rules and filing requirements with the relevant tax authority or a qualified tax professional.
Digital assets can be received through activities that do not resemble a conventional investment sale. Staking rewards, mining, airdrops, validator rewards, lending arrangements and decentralized-finance (DeFi) activities may create tax consequences or reporting obligations depending on the taxpayer’s circumstances, the nature of the transaction and the applicable jurisdiction.
Staking may involve receiving additional digital assets for participating in a proof-of-stake network or using a staking service. The tax treatment can depend on the legal and economic structure of the arrangement, the taxpayer’s control over the rewards and the rules in the relevant jurisdiction.
Maintain records of the receipt date and time, quantity, asset, wallet or account, transaction identifier and valuation evidence. Where an acquisition value establishes tax basis under local rules, preserve that value so it can be connected to a subsequent disposal.
Mining can generate digital assets in connection with providing computational resources to a blockchain network. The activity may be treated differently depending on local law and the taxpayer’s circumstances, including whether it constitutes a business, self-employment, an investment activity or another category.
Keep mining-pool statements, reward records, wallet transactions, relevant operating expenses and valuation evidence. Do not assume that all mining activities receive the same tax treatment or that every expense is deductible.
Airdropped and promotional tokens can raise classification questions. Their treatment may depend on the distribution mechanism, the recipient’s activities, whether the recipient performed services, whether the assets could be claimed or controlled, and the applicable tax rules.
Do not automatically classify every token appearing in a wallet as taxable income. First establish the nature of the distribution, the recipient’s rights and control, and the relevant facts. Record the distribution details, claim activity, timestamps, token quantities and available valuation evidence.
DeFi protocols can combine lending, borrowing, liquidity provision, swaps, rewards and automated smart-contract interactions. One transaction may represent several economically distinct events, so its tax classification should not be determined solely by a blockchain explorer’s label or the name of a protocol function.
Review the transaction sequence, assets transferred, rights received, fees charged and economic outcome. Where the treatment is uncertain, document the relevant facts and obtain jurisdiction-specific advice before finalizing the tax position.
Liquidity-pool participation may involve deposits, withdrawals, token exchanges, fees, rewards and changes in the assets held. Each component should be evaluated under the relevant tax framework rather than treating the entire interaction as one automatically taxable or nontaxable event.
Validator rewards should be documented with the relevant network, validator identity, wallet, receipt date, quantity, transaction identifier and valuation evidence. The timing of tax recognition depends on the applicable rules and the circumstances of the reward arrangement.
There is no single worldwide recognition rule covering every form of digital-asset income. Depending on the jurisdiction and transaction, relevant factors may include when an asset is received, when it becomes accessible, whether the taxpayer has control over it, the contractual arrangement and the nature of the underlying activity.
Review: Reward structure, control, receipt or crediting events, and local recognition rules.
Keep: Timestamps, quantities, wallet records, transaction IDs and valuation evidence.
Review: Whether the activity is classified as a business, self-employment, investment activity or another category.
Keep: Mining logs, reward statements, expenses, wallet data and valuations.
Review: Distribution terms, eligibility, claim rights, access to the tokens and local rules.
Keep: Distribution records, eligibility evidence, claim timestamps and valuation data.
Review: The economic substance of each protocol interaction and any associated rights or obligations.
Keep: Protocol records, transaction hashes, token movements, fees and valuations.
Review: Reward-crediting, compounding, accessibility and control under applicable local rules.
Keep: Validator logs, reward transactions, timestamps and historical valuation evidence.
Review: Deposits, withdrawals, interest, rewards, swaps and other potentially distinct events.
Keep: Protocol statements, wallet activity, token quantities, fees and transaction context.
Complex DeFi activity often requires more than importing centralized exchange statements. A complete digital-asset tax ledger should reconcile wallet addresses, transaction hashes, protocol activity, token quantities, transaction values, fees and ownership information before the tax position is finalized.
For further analysis of DeFi activity and digital-asset research workflows, see:
DeFi Risk Analysis — protocol-level risks and factors relevant to reviewing DeFi transactions.
Crypto Research Workspace — structured digital-asset research and transaction-analysis workflows.

Digital Asset Taxation extends beyond conventional cryptocurrencies. Non-fungible tokens (NFTs), utility tokens, governance tokens, stablecoins, wrapped assets and tokenized real-world assets can all raise tax questions when acquired, received, exchanged, sold or used in an economic activity.
Non-fungible tokens can represent artwork, collectibles, membership benefits, access rights, digital property or other interests. Their tax treatment may depend on how they were acquired, the rights they represent, the purpose for which they are held, the taxpayer’s activities and the circumstances of a subsequent transfer or sale.
For reliable tax records, preserve the acquisition date, purchase consideration, marketplace details, transaction fees, wallet ownership, relevant contract information, subsequent disposal details and valuation evidence. Where an NFT is received rather than purchased, document the circumstances of receipt and the applicable valuation method.
Utility and governance tokens can serve different economic purposes. They may provide platform access, voting rights, protocol participation, rewards or other benefits. Tax analysis should consider the rights actually attached to the token and the transaction undertaken rather than relying only on its marketing description.
Tokens received as compensation, rewards or through protocol participation may require a different analysis from tokens purchased and held as investments. Keep records showing why the token was received, what the recipient provided in return, any restrictions on its use, and the relevant transaction dates and values.
Stablecoins are designed to maintain a reference value, often against a fiat currency. However, their tax treatment is not necessarily identical across jurisdictions. A relatively stable price does not automatically mean that selling, exchanging, spending or otherwise transferring a stablecoin has no tax consequences.
For U.S. federal tax purposes, the IRS generally treats digital assets as property and includes stablecoins and NFTs within its digital-asset framework. The precise reporting obligations and tax consequences depend on the transaction and the rules applicable to the relevant tax year. Readers should consult current IRS guidance rather than assume that one reporting rule applies to every digital asset or transaction.
Wrapped assets can create classification questions because transactions may involve an underlying asset, a wrapped representation, a protocol interaction or a change in blockchain representation. Whether wrapping or unwrapping constitutes a taxable disposal, exchange or other relevant event depends on the applicable jurisdiction and the specific legal and economic facts.
A reliable tax ledger should preserve the relationship between the original asset and the wrapped representation. Record the assets transferred and received, quantities, transaction fees, timestamps, transaction hashes and the relevant protocol so that the full sequence can be reviewed.
Tokenized real-world assets may represent economic interests connected to physical property, contractual rights, fund interests, debt instruments or other underlying arrangements. The blockchain token may be only one part of the legal and economic structure.
Tax analysis should distinguish the digital representation from the underlying rights and obligations. Ownership terms, income distributions, transfers, fees, financing arrangements and the legal structure behind the token may all affect the result. Preserve offering documents, contracts, transaction records and distribution statements where relevant.
For additional context on the underlying asset and trust considerations, see RWA Tokenization & Trust.
This resource provides a separate research perspective on tokenized real-world assets while keeping this article focused on Digital Asset Taxation.
Creating and selling NFTs can raise different tax questions from purchasing NFTs as an investment. The taxpayer’s role, frequency of activity, contractual arrangements, source of payments and applicable business or income rules may all affect the analysis.
Royalty receipts should be documented separately from secondary-market sales and other transactions. Keep marketplace statements, smart-contract details, royalty records, wallet addresses, payment records and relevant expenses so recurring receipts can be reconciled to the underlying activity.
| Asset or Activity | Primary Tax Question | Documentation Focus |
|---|---|---|
| NFT Investment | How are acquisition and subsequent disposal treated? | Purchase records, fees, wallet ownership, valuation and sale details. |
| Token Trading | What event occurred, and how should it be classified? | Acquisition lots, trade history, fees, transaction values and exchange data. |
| Stablecoin Activity | Does the transaction create a gain, loss, income item or reporting obligation? | Acquisition and disposal values, fees and transaction purpose. |
| Wrapped Asset | What happened to the underlying asset and associated economic rights? | Original asset, wrapped token, protocol details and transaction sequence. |
| Real-World Asset Token | What legal or economic interest does the token represent? | Offering documents, ownership records, distributions and transfer records. |
| NFT Creation | How should creation, sales and royalty receipts be classified? | Sales records, royalty statements, relevant expenses and creator agreements. |
The same type of digital asset can raise different tax questions depending on how and why it is held or used. An individual investor, professional trader, creator, operating company and family office may be subject to different classification, calculation and reporting rules.
Digital asset tax obligations can differ for individual investors, people conducting trading or business activities, employees and contractors receiving crypto compensation, and companies holding digital assets. The applicable treatment depends on the activity, ownership structure, transaction details, tax residency and jurisdiction-specific rules. No single taxpayer category or trading pattern determines the result in every country.
These distinctions form part of the broader digital asset tax framework. Investors with cross-border holdings, international income or changing residence may also need to establish which country’s rules apply and whether more than one jurisdiction has a reporting claim.
Explore how tax residency, non-resident status and international circumstances can affect crypto tax obligations, including the jurisdiction-specific questions that a general tax overview cannot resolve.
Explore the Crypto Tax Residency Guide →
Tax residency can influence how cryptocurrency gains, digital asset income and reporting obligations are treated. The applicable rules may depend on where a taxpayer is considered resident, the nature and source of the income, and the laws of the relevant jurisdiction. Moving abroad or using an overseas exchange does not automatically remove existing tax obligations.
Residency is one part of the broader digital asset tax framework. When international moves, non-resident status or cross-border holdings complicate the analysis, the relevant countries’ rules must be considered before determining the applicable tax treatment.
Explore the dedicated guide for tax residency tests, international crypto activity, non-resident considerations and cross-border compliance. It covers the residency-specific questions that go beyond this overview of digital asset taxation.
Read the Crypto Tax Residency Guide →Tax residency and reporting obligations vary by jurisdiction and tax year. Confirm the applicable rules with the relevant tax authority or a qualified tax professional.

Digital Asset Taxation is jurisdiction-specific. The tax treatment of cryptocurrency, tokens, NFTs, staking rewards, DeFi transactions and other digital assets varies by country and may also differ according to taxpayer type and activity. Before applying a tax rule, establish the relevant tax year, residency, ownership structure, transaction type and applicable tax authority.
In the United States, federal tax treatment depends on the digital asset transaction and the taxpayer’s circumstances. Selling or exchanging an investment, receiving tokens as income, earning staking rewards and conducting business activities can raise different tax questions. Transfers between wallets controlled by the same taxpayer should also be distinguished from disposals to another party.
Taxpayers should retain acquisition costs, transaction dates, proceeds, fees, income records and supporting wallet or exchange histories. Consult current Internal Revenue Service (IRS) guidance for the applicable tax year and transaction.
In the United Kingdom, HM Revenue & Customs (HMRC) distinguishes between different cryptoasset activities and taxpayer circumstances. Investment disposals, income-producing activities and sufficiently organized trading may require different analyses under the relevant tax rules.
Records should allow acquisitions, disposals, fees, income events, transfers and valuations to be reconstructed for the relevant tax year. Use current HMRC guidance to determine the treatment applicable to the specific activity.
The European Union requires a distinction between EU-level cryptoasset regulation and direct taxation. EU regulatory and information-reporting frameworks can affect digital-asset activities, but income-tax and capital-gains treatment generally requires analysis under the applicable member state’s domestic tax rules.
Individuals and businesses operating across EU countries should establish their tax residence, identify the relevant national legislation and check any applicable cross-border reporting requirements. An EU-wide regulatory framework should not be assumed to create one uniform crypto income-tax treatment.
Canada applies its income-tax framework to digital-asset activities. Depending on the facts, transactions may be analyzed as business income or losses, capital gains or losses, or other income-producing activity. The classification can affect how amounts are calculated and reported.
Canadian taxpayers should maintain transaction histories, values, costs, fees and records explaining the purpose of their activities. Consult current Canada Revenue Agency (CRA) guidance for the relevant transaction and tax year.
Australia applies its own income-tax and capital-gains rules to cryptocurrency and other digital assets. Treatment can depend on whether an asset is held as an investment, used in business activities, received as income or disposed of in another transaction. The purpose and circumstances of the activity matter.
Australian taxpayers should keep transaction records and consult current Australian Taxation Office (ATO) guidance rather than importing assumptions from another country’s tax system.
Other countries and financial centers may apply different approaches to investment gains, ordinary income, business activity, withholding, digital-asset reporting and foreign holdings. Some jurisdictions may also distinguish between individuals, companies, funds and other entities.
Before relying on a comparison, identify the applicable local tax authority, residency rules, entity classification and transaction treatment. A rule that applies in one jurisdiction should not be presumed to apply elsewhere.
| Jurisdiction | Framework to examine | Key considerations | Official authority |
|---|---|---|---|
| United States | Federal income-tax and digital-asset reporting rules | Transaction type, taxpayer status, holding period and applicable federal or state rules | Internal Revenue Service (IRS) |
| United Kingdom | Income-tax and capital-gains rules | Individual or business status, income events and disposals | HM Revenue & Customs (HMRC) |
| European Union | Member-state taxation and applicable EU regulatory or reporting frameworks | Member state, residency, transaction type and taxpayer status | Relevant national tax authority and applicable EU institutions |
| Canada | Federal income-tax framework | Business versus investment activity, transaction classification and taxpayer circumstances | Canada Revenue Agency (CRA) |
| Australia | Income-tax and capital-gains framework | Purpose of holding, activity, taxpayer type and disposal | Australian Taxation Office (ATO) |
| Other jurisdictions | Applicable domestic tax and reporting framework | Residency, entity type, asset activity and local law | Relevant local tax authority |
Tax residence is an important starting point when comparing digital-asset tax rules. Residence, domicile, citizenship, source-of-income rules and entity location can have different legal meanings. Physical location or the country where an exchange account is maintained does not, by itself, establish the complete tax position.
Cross-border transactions can introduce additional questions when taxpayers use foreign exchanges, hold assets through overseas entities, receive digital-asset income from international counterparties or relocate between countries. Ownership, transaction details, source rules, treaty provisions and reporting obligations should be evaluated separately under the applicable laws.
Digital asset tax compliance requires a reliable record of cryptocurrency transactions, the correct tax classification of each relevant event, and reporting that follows the rules applicable to the taxpayer and tax year. Exchange statements, wallet histories, transaction valuations, and supporting documents help establish the information needed to calculate taxable gains, losses, income, and other reportable amounts.
Transactions that may require tax analysis or reporting include cryptocurrency sales and exchanges, payments made with digital assets, income received in tokens, staking and mining rewards, NFT transactions, and certain decentralized-finance activities. The applicable treatment depends on the transaction, the taxpayer’s circumstances, and local law. Not every blockchain movement creates a taxable event, and not every transaction is subject to the same disclosure requirements.
Transfers between wallets or accounts controlled by the same taxpayer should be distinguished from disposals to another party. Recording both sides of a transfer helps reconcile asset quantities and preserve the original acquisition history without automatically treating the movement as a sale.
The forms, schedules, disclosures, deadlines, and information-reporting obligations associated with digital assets vary by jurisdiction, taxpayer type, transaction category, and tax year. Determine which requirements apply to the actual activity rather than assuming that a single crypto tax form covers every transaction. Third-party reporting documents can help verify transaction data, but they may not capture every relevant event or resolve the taxpayer’s complete tax position.
Tax records should allow the taxpayer or a reviewer to trace a reported amount back to the underlying transaction. Depending on the activity and applicable rules, this may require acquisition and disposal dates, asset quantities, transaction values, fees, wallet or exchange details, cost-basis information, and evidence supporting the classification of income or gains and losses.
Exchange records and blockchain data provide different parts of the transaction history. Exchange exports may document trades and account activity, while on-chain records can help establish transfers, token movements, and smart-contract interactions. Reconciliation connects these sources, identifies duplicate or missing entries, distinguishes internal transfers from disposals, and preserves the acquisition history needed for accurate tax calculations.
Missing transaction data should be investigated before tax calculations are finalized. Depending on the circumstances, reconstruction may involve exchange statements, historical wallet activity, blockchain records, bank statements, invoices, custody reports, or previous tax filings. Keep verified facts separate from estimates, document the method used to reconstruct missing information, and investigate discrepancies rather than assuming that unexplained balances represent income or gains.
Digital asset reporting can involve specialized rules that require more detailed analysis than a general compliance overview can provide. Use the relevant guide below when your main question concerns a specific transaction type, cross-border situation, or reporting tool.
Explore loss realization, wash-sale considerations, and jurisdiction-specific tax strategies.
Read the tax-loss harvesting guide →Review staking reward taxation, valuation, recordkeeping, and applicable reporting requirements.
Read the staking tax guide →Understand residency, non-resident circumstances, and cross-border crypto tax questions.
Read the tax residency guide →Compare tools for importing transaction data, reconciling activity, and preparing tax reports.
Compare crypto tax software →Educational information only; not individualized tax, legal, or accounting advice. Digital asset tax treatment, reporting obligations, and record-retention requirements vary by jurisdiction and tax year. Verify the applicable rules with the relevant tax authority or a qualified professional.
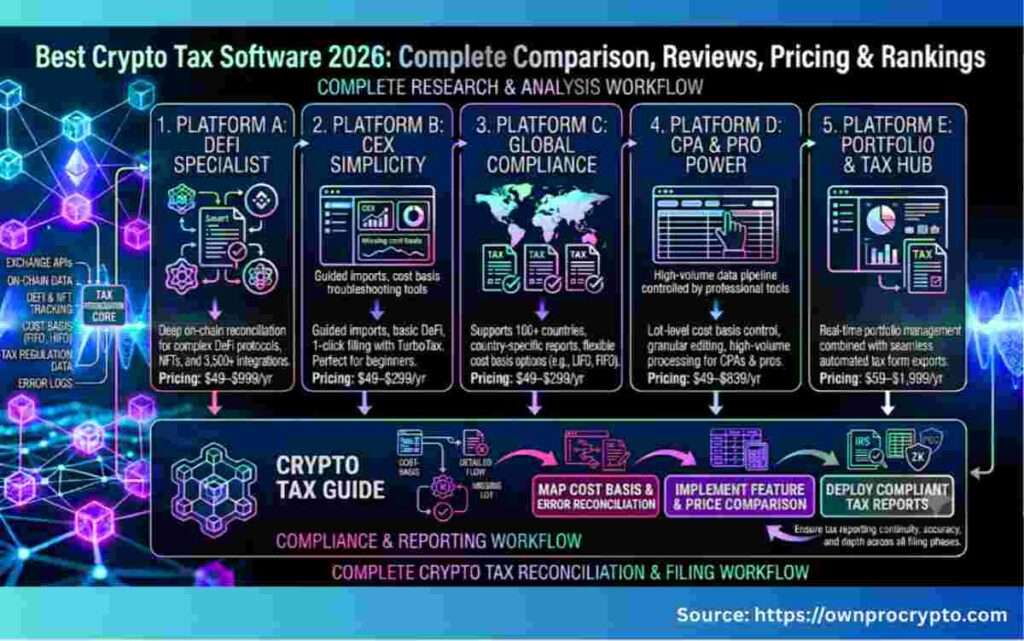
Digital asset tax tracking helps organize the transaction records needed to calculate and report cryptocurrency gains, losses, income, and other tax-relevant amounts. Tracking tools can consolidate information from exchanges, wallets, custodians, and supported blockchain networks, but the resulting tax ledger still needs to be checked against source records and the rules applicable to the taxpayer.
Cryptocurrency activity may span several exchanges, self-custody wallets, custodians, blockchain networks, and decentralized applications. Each source may record activity differently, and a single movement of assets may appear in more than one account history. Tracking systems help bring these records together so that transactions can be reviewed as part of one coherent tax ledger.
Exchange histories and wallet records provide complementary information. Exchange exports may show account-level trades, deposits, withdrawals, and fees, while wallet histories and blockchain records help trace movements between addresses. Matching these records can help determine whether an apparent deposit or withdrawal is an internal transfer, a transaction involving another party, or an unresolved event requiring further investigation.
Preserve original exports and transaction evidence before correcting or classifying imported records. Record the reason for manual adjustments so that the final tax ledger can be traced back to its underlying sources.
A tax tracking system should preserve the acquisition history needed to calculate gains or losses when a relevant disposal occurs. Depending on the jurisdiction and activity, useful records may include acquisition dates, quantities, acquisition values, fees, asset identifiers, disposal proceeds, and the basis method used.
When an asset has been acquired in multiple transactions, the reported basis must follow the applicable identification, matching, or pooling rules. Software-generated calculations should be checked against those rules rather than assumed to be correct simply because the platform has produced a completed report.
Decentralized-finance interactions, staking activity, token bridges, and smart-contract transactions can require more context than a standard exchange trade. Automated imports may identify token movements without fully explaining the economic activity or the rights involved. Review unusual or complex transactions using the available protocol records, transaction details, valuation evidence, and applicable tax rules.
For these activities, retain relevant transaction identifiers, originating and destination networks, asset quantities, timestamps, fees, and supporting documentation. The classification of a transaction should be based on its facts and applicable law, not solely on the label assigned by a tracking platform.
| Approach | Best Suited To | Main Limitation | Essential Control |
|---|---|---|---|
| Manual Records | Small, straightforward transaction histories | Time-consuming as transaction volume increases | Consistent records and source-document retention |
| Spreadsheets | Structured records and customized calculations | Formula errors, inconsistent imports, and version conflicts | Formula validation, backups, and controlled edits |
| Tax Tracking Software | Consolidating supported accounts and larger transaction histories | Missing integrations or incorrect classifications can affect results | Reconciliation, exception review, and verification of tax rules |
| Professional Review | Complex transactions, uncertain classifications, and filing review | Requires appropriate professional expertise and supporting records | Clear documentation and a review trail |
Before relying on a completed tax report, check for missing transactions, duplicate entries, unmatched transfers, unexplained balance changes, incorrect asset identifiers, incomplete acquisition histories, and inconsistent valuation data. Confirm that the selected calculation method and transaction classifications follow the applicable jurisdiction’s rules.
Choosing a tracking platform is a separate decision from understanding the tax rules themselves. Use the Best Crypto Tax Software comparison to explore software options, supported integrations, and features relevant to your transaction history.
For additional operational context, see the Crypto Research Workspace and Crypto Security. These resources complement transaction research and record protection without replacing tax-specific analysis.
Educational information only; not individualized tax, legal, or accounting advice. Tracking capabilities, tax calculations, and reporting requirements vary by platform, jurisdiction, and tax year. Verify important calculations and filing requirements against the applicable rules and source records.

Digital asset tax compliance requires more than calculating cryptocurrency gains, losses and income. Taxpayers also need to identify reporting errors, investigate incomplete records, support transaction classifications and retain evidence for the tax positions they report. Effective controls help connect each reported amount to the underlying activity and the rules applicable to the relevant jurisdiction and tax year.
Core compliance principle: Every material tax calculation should be traceable to its source records, transaction classification, valuation method and applicable tax rule. A complete audit trail helps explain how the reported result was determined.
Cryptocurrency transactions may pass through multiple exchanges, self-custody wallets, custodians and decentralized protocols. Errors can arise when records are incomplete, transactions are incorrectly classified or supporting evidence cannot be reproduced. The following controls address common weaknesses without assuming that every blockchain transaction creates a taxable event.
Missing exchange exports, wallet histories or transaction details can leave gaps in the information used to prepare a tax return.
Unverified acquisition costs, valuations, fees or basis adjustments can affect reported gains, losses and income.
Internal transfers, disposals, rewards and other receipts may be assigned the wrong tax treatment if their context is unclear.
Missing source documents, undocumented adjustments or unexplained discrepancies can make a reported tax position difficult to substantiate.
Use this framework to identify potential reporting weaknesses and establish appropriate review procedures. The consequences of an error depend on the facts, applicable law and relevant filing requirements.
| Risk | What to Check | Practical Control |
|---|---|---|
| Missing transactions | Unexplained differences between account statements, wallet records and the tax ledger. | Reconcile available source records and investigate unresolved differences. |
| Cost-basis errors | Acquisition history, asset quantities, basis adjustments and disposal calculations. | Retain acquisition evidence and apply the method required by the relevant jurisdiction. |
| Transfer misclassification | Whether the transaction was an internal movement or an event involving another party. | Match transfers using transaction identifiers, timestamps, quantities and ownership records. |
| Income omissions | Receipts from staking, mining, compensation, airdrops or other activities. | Review incoming transactions and document their source, circumstances and tax classification. |
| Unsupported valuations | Whether recorded values can be linked to a source and transaction time. | Preserve valuation evidence and explain the method used. |
| Missing documentation | Whether calculations and adjustments can be reproduced from retained evidence. | Maintain source documents, review notes and a record of material corrections. |
A defensible digital asset tax record should connect the original transaction to its classification, calculation and final reporting treatment. Blockchain data can help establish that a movement occurred, while exchange statements, contracts, wallet ownership records and other documents may be needed to explain its economic context.
Before finalizing a return, review material discrepancies, unmatched transfers, incomplete acquisition histories, unsupported valuations and unexplained adjustments. Record how each issue was resolved and retain enough evidence for the calculation to be reproduced later.
When transaction information is missing, investigate the available evidence before finalizing the tax calculation. Depending on the circumstances, useful sources may include historical exchange statements, blockchain records, wallet histories, bank records, invoices, custody statements and previous tax documents.
Important: Do not invent a cost basis, assume an unexplained transaction is tax-free or treat an estimated value as a verified fact. Document any reconstruction method, distinguish estimates from confirmed information and seek qualified advice when a material tax position cannot be supported.
If a tax authority requests information about digital asset activity, identify the transactions and tax periods covered by the request, gather the relevant source records, reproduce the calculations and explain the methods used. Provide information in accordance with the authority’s instructions and applicable deadlines.
If an earlier filing contains an error, the appropriate correction procedure depends on the jurisdiction, filing period and nature of the issue. A request for information does not automatically establish that an error occurred, and the appropriate response depends on the facts. Consider professional tax assistance when the matter is complex, material or involves multiple jurisdictions.
| Evidence Layer | Examples | Why It Matters |
|---|---|---|
| Transaction source | Exchange statements, transaction hashes, wallet histories and account records. | Establishes the activity included in the calculation. |
| Ownership and context | Wallet ownership records, contracts, payment details and protocol documentation. | Helps explain who controlled the assets and what occurred. |
| Tax calculation | Acquisition records, proceeds, valuations, fees and basis adjustments. | Supports reported gains, losses, income and other relevant amounts. |
| Classification and review | Applicable guidance, reconciliation notes, adjustment explanations and review records. | Documents why the tax treatment was selected and how exceptions were resolved. |
Related OwnProCrypto research
Tax compliance also depends on protecting access to wallets, accounts and supporting records. See Crypto Security for digital asset security practices and Crypto Security Checklist for a practical review of security controls.
Key takeaway: Reliable digital asset tax compliance combines accurate transaction data, jurisdiction-appropriate tax treatment, documented calculations and a reproducible review trail. The objective is to ensure that reported amounts can be explained and supported by the available evidence.

Digital asset tax compliance for institutions and family offices requires accurate transaction records, clear ownership attribution, consistent cost-basis information, and reporting procedures appropriate to the entities and jurisdictions involved. Organizations holding cryptocurrency through multiple wallets, exchanges, custodians, funds, or investment vehicles need to connect their transaction histories with accounting records and applicable tax requirements.
Institutional principle: Tax reporting should connect asset ownership, custody records, transaction histories, tax calculations, reconciliation, and final reporting in a traceable process.
Institutional tax reporting typically involves several functions. Their responsibilities should be defined according to the organization’s structure, transaction volume, internal controls, and use of external service providers.
Clear responsibilities help prevent incomplete records, inconsistent classifications, and unsupported tax calculations.
Family offices may hold digital assets directly or through companies, trusts, funds, custodians, or other investment structures. Tax reporting should identify the relevant legal owner, account or wallet, acquisition history, transaction activity, and applicable reporting entity.
A consolidated record can help distinguish transactions belonging to different entities, reconcile portfolio activity, and provide tax professionals with the documentation needed to review the organization’s tax position. The appropriate treatment depends on the legal structure and the tax rules governing each entity.
Institutional digital asset records should connect asset ownership, custody information, transaction details, acquisition history, valuations, and tax calculations. Useful documentation may include the following records.
| Record | Compliance Purpose |
|---|---|
| Entity ownership and account mapping | Identifies the entity associated with each asset and account. |
| Wallet and custodian records | Supports reconciliation of balances and asset movements. |
| Transaction histories | Documents dates, quantities, transaction identifiers, and relevant activity. |
| Acquisition and tax-lot records | Supports cost-basis calculations under the applicable rules. |
| Valuation evidence | Documents values used in relevant tax calculations. |
| Review and adjustment records | Explains corrections, unresolved discrepancies, and material classification decisions. |
Custodian statements, blockchain records, accounting systems, and tax software each provide different information. None should automatically be treated as a complete record of the taxpayer’s obligations. Reconcile the available sources and investigate material discrepancies before finalizing tax reporting.
Organizations should preserve acquisition records and document the methods used to calculate gains or losses. Transfers between accounts controlled by the same taxpayer should be distinguished from disposals or other transactions that may have tax consequences. Recordkeeping should maintain the connection between the original acquisition and any subsequent transaction.
Jurisdiction matters: Cost-basis identification, pooling, allowable adjustments, and reporting requirements vary by jurisdiction and tax year. Institutional procedures should reflect the rules applicable to the relevant entity and transactions rather than assuming that a single method applies worldwide.
External tax advisers, accountants, custodians, and technology providers may support different stages of the compliance process. Organizations should establish which records each provider receives, how discrepancies are resolved, who reviews the calculations, and how the final reported figures can be traced back to their source documentation.
Outsourcing tax preparation or data processing does not eliminate the need to review the accuracy and completeness of the information used for reporting.
Institutional tax reporting also depends on reliable custody practices, account protection, and transaction records. For related operational guidance, explore Crypto Security and the Crypto Security Checklist.
For a broader explanation of cryptocurrency tax rules, taxable transactions, cost basis, income, and reporting obligations, continue with the relevant sections of this Digital Asset Taxation guide.
Compliance principle: A reliable institutional tax process connects ownership, custody, transaction records, tax classification, calculations, reconciliation, review, and reporting. Maintain supporting evidence for material tax positions and verify the requirements applicable to each entity, transaction, and tax year.
Educational information only; not individualized tax, legal, or accounting advice. Consult the relevant tax authority or a qualified professional for jurisdiction-specific requirements.

A reliable Digital Asset Taxation process should move in a defined sequence: collect the underlying transaction data, classify what happened, establish the relevant tax basis, calculate the result, reconcile the records, report where required, and retain supporting documentation.
Bring together exchange records, wallet activity, on-chain transactions, brokerage or custodian statements, token receipts, disposals, transfers and other relevant digital-asset records.
Distinguish purchases, sales, swaps, transfers, income, staking, mining, airdrops, DeFi activity, gifts and other transaction types before applying the relevant tax treatment.
Identify acquisition information, applicable costs, transaction fees, dates and other data needed to establish the appropriate tax basis under the rules applicable to the taxpayer.
Apply the relevant jurisdictional rules to calculate gains, losses, income or other reportable amounts. Keep calculations traceable back to the underlying transaction records.
Check that transfers between wallets, exchanges and custodians are not incorrectly treated as disposals or duplicated as separate economic events.
Confirm the rules, definitions, forms, deadlines and reporting obligations applicable to the taxpayer’s jurisdiction and tax year. Do not assume that one country’s treatment applies globally.
Map the reconciled transaction data to the forms, schedules, disclosures or information-reporting requirements that actually apply to the taxpayer.
Preserve transaction histories, statements, valuation evidence, calculations, invoices, wallet records and other supporting documentation for the period required by applicable law.
For the operational side of digital-asset compliance, you can also review Crypto Security Checklist for control-oriented security review, and Crypto Security for broader digital-asset security concepts. These resources support the compliance framework without replacing jurisdiction-specific tax advice.
Important: Tax treatment, filing obligations and record retention requirements vary by jurisdiction and taxpayer circumstances. Verify current rules with the applicable tax authority and qualified professional before filing.
Explore the wider OwnProCrypto research cluster for connected guidance on digital-asset taxation, security, research, tokenization and regulatory developments. Use the cluster navigator to discover related topics, move between supporting resources and return to the main subject without losing the context of your research.
Start with the topic you need, explore connected research, and follow the relevant links to move between the pillar and its supporting cluster pages.
These supporting resources address related subject areas that can help readers understand the wider operational, technical and regulatory environment surrounding digital assets.
Organize research, evaluate digital-asset projects and maintain supporting due-diligence information.
Review custody arrangements, access controls and security procedures relevant to protecting digital assets and their records.
Explore tokenized real-world assets, ownership arrangements and trust considerations.
Review regulatory context relevant to stablecoins and digital-asset compliance research.
For digital-asset protection, visit Crypto Security. For practical security controls, open the Crypto Security Checklist. To continue the main topic, return to Digital Asset Taxation.
Research note: These resources provide educational and research context. They do not replace jurisdiction-specific tax, legal, accounting or investment advice.
These frequently asked questions explain Digital Asset Taxation, cryptocurrency tax, crypto taxes, capital gains, taxable income, cost basis, transaction history, tax reporting, tax software, Form 1099-DA, and the compliance considerations that affect individual investors, businesses, institutions, and family offices. Answers are educational and jurisdiction-dependent.
Use these related resources to explore the operational, security, regulatory, and research topics that support a broader digital-asset understanding. Digital Asset Taxation remains the primary subject of this guide.
Organize digital-asset research, supporting evidence, and due-diligence records.
Explore research workspace →Review wallet protection, custody risks, and digital-asset security concepts.
Explore crypto security →Use a structured checklist to review operational safeguards and access controls.
Review security checklist →Explore tokenized real-world assets, ownership structures, and trust considerations.
Explore RWA research →Review regulatory considerations affecting stablecoins and digital-asset markets.
Explore stablecoin regulation →Research note: This FAQ provides general educational information, not individualized tax, legal, accounting, or investment advice. Provider names are included for informational context and do not constitute an endorsement. Verify current rules, product capabilities, pricing, and filing requirements independently.
| Asset ID | Asset | Quantity | Cost Basis ($) | Market Value ($) | Unrealized P/L ($) |
|---|---|---|---|---|---|
| DAT001 | Bitcoin | 5.0 | 250,000 | 300,000 | 50,000 |
| DAT002 | Ethereum | 100 | 280,000 | 340,000 | 60,000 |
| DAT003 | Solana | 2,500 | 220,000 | 260,000 | 40,000 |
| DAT004 | Chainlink | 6,000 | 90,000 | 105,000 | 15,000 |
| DAT005 | Avalanche | 3,500 | 130,000 | 150,000 | 20,000 |
| Tx ID | Date | Asset | Transaction Type | Value ($) | Tax Event |
|---|---|---|---|---|---|
| TX001 | 05-Jan-2026 | BTC | Sale | 50,000 | Yes |
| TX002 | 12-Jan-2026 | ETH | Swap | 12,000 | Yes |
| TX003 | 22-Jan-2026 | SOL | Purchase | 8,000 | No |
| TX004 | 03-Feb-2026 | LINK | Sale | 5,000 | Yes |
| TX005 | 15-Feb-2026 | AVAX | Transfer | 3,500 | Depends |
| Trade ID | Asset | Sale Date | Gain/Loss ($) | Classification | Status |
|---|---|---|---|---|---|
| RL001 | BTC | 10-Jan-2026 | 12,000 | Gain | Closed |
| RL002 | ETH | 18-Feb-2026 | -5,000 | Loss | Closed |
| RL003 | SOL | 12-Mar-2026 | 8,000 | Gain | Closed |
| RL004 | LINK | 25-Mar-2026 | -2,500 | Loss | Closed |
| RL005 | AVAX | 15-Apr-2026 | 3,000 | Gain | Closed |
| Asset | FIFO | LIFO | HIFO | Recommended Method |
|---|---|---|---|---|
| BTC | 10,000 | 8,500 | 6,500 | HIFO |
| ETH | 12,000 | 10,500 | 8,000 | HIFO |
| SOL | 8,000 | 7,500 | 6,000 | HIFO |
| LINK | 5,000 | 4,500 | 3,800 | HIFO |
| AVAX | 6,500 | 5,800 | 4,900 | HIFO |
| Asset | Unrealized Loss ($) | Holding Period | Harvest Potential | Priority |
|---|---|---|---|---|
| ETH | 5,000 | Long-Term | High | High |
| LINK | 2,500 | Short-Term | Medium | Medium |
| AVAX | 3,000 | Short-Term | Medium | Medium |
| MATIC | 4,000 | Long-Term | High | High |
| UNI | 1,500 | Short-Term | Low | Low |
| Asset | Sale Date | Repurchase Date | Days Between | Risk Level | Status |
|---|---|---|---|---|---|
| BTC | 05-Jan | 15-Jan | 10 | High | Review |
| ETH | 12-Feb | 20-Mar | 36 | Low | Clear |
| SOL | 15-Mar | 25-Mar | 10 | High | Review |
| LINK | 10-Apr | 20-May | 40 | Low | Clear |
| AVAX | 15-May | 30-May | 15 | Medium | Review |
| Asset | Rewards Earned | Value ($) | Taxable Income | Status |
|---|---|---|---|---|
| ETH | 8.5 | 22,000 | Yes | Active |
| SOL | 320 | 48,000 | Yes | Active |
| ADA | 2,000 | 9,500 | Yes | Active |
| DOT | 450 | 4,800 | Yes | Active |
| ATOM | 180 | 2,200 | Yes | Active |
| Operation | Asset | Coins Earned | Value ($) | Taxable Income |
|---|---|---|---|---|
| Mining Farm A | BTC | 1.2 | 72,000 | Yes |
| Mining Farm B | BTC | 0.8 | 48,000 | Yes |
| GPU Cluster A | ETC | 4,000 | 16,000 | Yes |
| ASIC Unit A | LTC | 800 | 7,500 | Yes |
| ASIC Unit B | DOGE | 50,000 | 5,500 | Yes |
| Activity | Transactions | Taxable Event | Estimated Impact |
|---|---|---|---|
| Yield Farming | 75 | Yes | High |
| Liquidity Mining | 60 | Yes | High |
| Lending Interest | 50 | Yes | Medium |
| Borrowing | 30 | Depends | Low |
| Governance Rewards | 20 | Yes | Medium |
| NFT Asset | Purchase ($) | Sale ($) | Gain/Loss ($) | Tax Status |
|---|---|---|---|---|
| NFT Alpha | 10,000 | 14,000 | 4,000 | Gain |
| NFT Beta | 7,000 | 5,000 | -2,000 | Loss |
| NFT Gamma | 15,000 | 18,000 | 3,000 | Gain |
| NFT Delta | 4,000 | 2,000 | -2,000 | Loss |
| NFT Omega | 8,000 | 12,000 | 4,000 | Gain |
| Stablecoin | Volume ($) | Transactions | Taxable Events | Risk Rating |
|---|---|---|---|---|
| USDC | 500,000 | 120 | Medium | Low |
| USDT | 800,000 | 180 | Medium | Medium |
| DAI | 150,000 | 50 | Low | Low |
| PYUSD | 90,000 | 25 | Low | Low |
| EURC | 75,000 | 20 | Low | Low |
| Event | Asset | Value Received ($) | Taxable Income | Status |
|---|---|---|---|---|
| Airdrop A | XYZ | 2,000 | Yes | Recorded |
| Airdrop B | ABC | 1,500 | Yes | Recorded |
| Fork A | BTCX | 5,000 | Yes | Recorded |
| Fork B | ETHX | 3,000 | Yes | Recorded |
| Governance Drop | GOV | 1,200 | Yes | Recorded |
| Country | Days Present | Tax Resident | Filing Required | Status |
|---|---|---|---|---|
| UAE | 210 | Yes | Yes | Active |
| UK | 35 | No | No | Active |
| Portugal | 45 | No | No | Active |
| Singapore | 25 | No | No | Active |
| Switzerland | 20 | No | No | Active |
| Jurisdiction | Capital Gains | Staking Tax | Mining Tax | Complexity |
|---|---|---|---|---|
| USA | Yes | Yes | Yes | High |
| UK | Yes | Yes | Yes | High |
| UAE | Generally Favorable | Depends | Depends | Low |
| Singapore | Generally Favorable | Depends | Depends | Low |
| Switzerland | Varies | Varies | Varies | Medium |
| Country Pair | Treaty Exists | Relief Available | Status |
|---|---|---|---|
| UAE–UK | Yes | Yes | Active |
| UAE–India | Yes | Yes | Active |
| UK–Singapore | Yes | Yes | Active |
| Portugal–USA | Yes | Yes | Active |
| Switzerland–Germany | Yes | Yes | Active |
| Requirement | Status | Last Review | Owner |
|---|---|---|---|
| Trade History | Complete | Monthly | Finance |
| Wallet Records | Complete | Monthly | Operations |
| Exchange Statements | Complete | Quarterly | Accounting |
| Tax Reports | Complete | Quarterly | Tax Advisor |
| Compliance Records | Complete | Monthly | Compliance |
| Planning Area | Progress | Priority | Status |
|---|---|---|---|
| Capital Gains Review | 90% | High | Active |
| Loss Harvesting | 80% | High | Active |
| Staking Review | 100% | Medium | Complete |
| NFT Reporting | 95% | Medium | Complete |
| DeFi Reporting | 85% | High | Active |
| Scenario | Tax Liability ($) | Savings ($) | Outcome |
|---|---|---|---|
| No Planning | 120,000 | 0 | Baseline |
| Basic Planning | 105,000 | 15,000 | Improved |
| Harvesting Strategy | 90,000 | 30,000 | Strong |
| Advanced Planning | 75,000 | 45,000 | Excellent |
| Institutional Structure | 60,000 | 60,000 | Optimized |
| Risk ID | Risk Description | Probability | Impact | Status |
|---|---|---|---|---|
| R001 | Missing Records | Medium | High | Active |
| R002 | Incorrect Cost Basis | Medium | High | Active |
| R003 | DeFi Reporting Errors | Medium | High | Active |
| R004 | Residency Misclassification | Low | High | Active |
| R005 | Audit Exposure | Low | Critical | Active |
| Category | Current Score | Target Score | Gap |
|---|---|---|---|
| Record Keeping | 95 | 100 | 5 |
| Compliance | 94 | 100 | 6 |
| Cost Basis Management | 92 | 98 | 6 |
| Tax Planning | 90 | 98 | 8 |
| Audit Readiness | 96 | 100 | 4 |