infographic of site logo for contact us

OwnProCrypto.com

Use our Crypto Search Engine 🔍 to find the topics and keywords you're looking for.

Updated September 2026

Stablecoin Regulations & CBDC (2026): Key Rules, Risks, & the Future of Digital Money

Stablecoin regulation is no longer just a proposal. In 2026, major financial jurisdictions are moving from broad policy discussions toward licensing, reserve, redemption, disclosure, compliance and supervision requirements. The United States now has a federal framework for payment stablecoins through the GENIUS Act, the European Union has its MiCA framework, Hong Kong has established a licensing regime for fiat-referenced stablecoin issuers, and the UK is building its own staged regime.

Short answer: A stablecoin is not regulated by one universal global rule. The legal treatment depends on the token, the issuer, the reserve structure, the activity being performed and the jurisdiction. For a business, the most important questions are who issues the stablecoin, what backs it, whether holders have a redemption right, whether the issuer is licensed, and what the business is doing with the token.
USER ── deposits $1,000 USD ──► RESERVE / ISSUER ── mints 1,000 TOKENS ──► WALLET

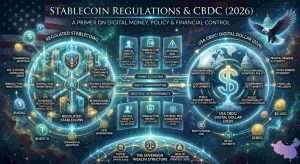
Infographic of Stablecoin Regulations & CBDC (2026) shows A Primer on Digital Money, Policy & Financial Control

Latest Developments (2026 Update)

Recent global developments:

  • Governments accelerating stablecoin regulatory frameworks
  • Central banks expanding CBDC pilot programs and testing phases
  • Increased focus on compliance, transparency, and reserve backing
  • Growing debate over privacy vs control in digital currencies

The direction is clear:
digital money is becoming state-aligned infrastructure

Table of Contents

Stablecoin Regulation at a Glance

The easiest way to understand the 2026 landscape is to stop treating stablecoins as one legal category. Regulators increasingly distinguish between payment-oriented stablecoins, electronic money or asset-referenced tokens, other cryptoassets, and stablecoins that may have investment or securities characteristics.

GENIUS Act

The US has a federal framework specifically addressing payment stablecoins. The framework focuses on permitted issuers, eligible reserves, redemption, disclosure, supervision and related financial-crime controls.

European Union

MiCA

MiCA creates a harmonised framework for cryptoassets in the EU. Stablecoin-like assets are primarily addressed through the categories of e-money tokens and asset-referenced tokens.

United Kingdom

Staged framework

The UK is developing a separate regulatory architecture covering cryptoasset activities and stablecoin payments, with major implementation milestones extending beyond 2026.

Global picture

Different rules, similar concerns

Across jurisdictions, regulators repeatedly focus on reserve quality, redemption, governance, operational resilience, financial crime controls and consumer protection.

Stablecoin or digital token
↓
What does the token promise?
↓
Who issues it and what backs it?
↓
What activity is being performed?
↓
Which jurisdiction and regulator apply?

What regulators normally examine

Reserve assets

Regulators may require specified reserve assets, segregation, custody standards, valuation controls and reporting.

Redemption

A major regulatory question is whether holders can redeem the token and under what conditions, timing and fees.

Issuer

The identity, legal status, governance and financial condition of the issuer can determine which regulatory framework applies.

The Digital Money Landscape

                    DIGITAL MONEY

                           │
         ┌─────────────────┴─────────────────┐
         │                                   │

         ▼                                   ▼

   Private Digital Money              Public Digital Money

         │                                   │

         ▼                                   ▼

     Stablecoins                         CBDCs

         │                                   │

         ▼                                   ▼

 USDC, USDT, PYUSD                 Digital Dollar
                                  Digital Euro
                                  Digital Yuan
 

Distribution

Offering a stablecoin to customers can create different obligations from simply using a third-party stablecoin for settlement.

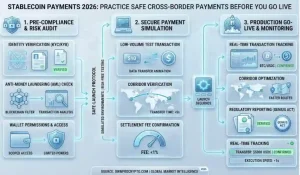
Infographic of Stablecoin Payment System 2026. Practice Safe Cross-Border Payments Before You Go Live

How Stablecoin Regulation Is Changing in 2026

For much of the industry’s early history, stablecoins operated under fragmented regulatory frameworks. That environment is changing rapidly.

Regulators increasingly view stablecoins as an important component of digital payment infrastructure. As adoption expands, governments are implementing clearer standards designed to reduce systemic risk while encouraging innovation.

The focus of modern stablecoin regulation generally centers on four objectives:

  • Reserve transparency
  • Consumer protection
  • Financial stability
  • Anti-money laundering compliance

These developments are reshaping how institutions evaluate stablecoin adoption and digital payment systems.


How Stablecoins Are Issued

Understanding stablecoin regulation begins with understanding how most fiat-backed stablecoins enter circulation.

User Deposits $1,000
          │
          ▼
Reserve Account
(Cash/Treasuries)
          │
          ▼
Stablecoin Issuer
          │
          ▼
1,000 Stablecoins Minted
          │
          ▼
User Wallet

The regulatory focus is simple:

Can the issuer reliably redeem those tokens for their underlying value?

That question drives most modern stablecoin compliance frameworks.


Types of Stablecoins

Not all stablecoins operate in the same manner.

Fiat-Backed Stablecoins

These assets are supported by reserve holdings such as:

  • Cash deposits
  • Treasury bills
  • Money market instruments

Examples include widely used payment stablecoins designed for enterprise settlement and cross-border transfers.

Crypto-Backed Stablecoins

These systems use digital assets as collateral and often require over-collateralization to maintain stability.

Algorithmic Stablecoins

Algorithmic models attempt to maintain price stability through supply management rather than direct reserve backing.

Following several high-profile failures, regulators have generally taken a more cautious view toward algorithmic stabilization mechanisms.

Infographic of Stablecoin Payments 2026. Exploring Architecting Sovereign Finance USDT Use Cases

CBDC vs Stablecoin: Understanding the Differences

One of the most common questions in digital finance is:

CBDC vs stablecoin: what is the difference?

Although both are digital representations of value, they serve fundamentally different purposes.

Table: Stablecoins vs CBDCs

FeatureStablecoinsCBDCs
IssuerPrivate companiesCentral banks
Legal Tender StatusNoTypically Yes
Reserve ModelCash, Treasuries, liquid assetsSovereign currency
GovernanceCorporate or protocol basedGovernment controlled
PrivacyGenerally higherOften lower
SettlementNear real-timeReal-time potential
Innovation SpeedFasterSlower
Regulatory OversightGrowingDirect government oversight

Stablecoins and CBDCs Compared

Private Sector Model

Users
  │
  ▼
Stablecoin Issuer
  │
  ▼
Reserve Assets
  │
  ▼
Redemption
────────────────────────

Public Sector Model Users │ ▼ Central Bank │ ▼ CBDC Ledger │ ▼ Digital Currency

Why Governments Are Exploring CBDCs

Governments are exploring CBDCs for several reasons.

Payment Efficiency

Digital settlement infrastructure can improve transaction speed and reduce operational friction.

Financial Inclusion

Some policymakers view CBDCs as a tool for expanding access to financial services.

Monetary Policy Transmission

Digital systems may provide more direct channels for distributing funds throughout the economy.

Payment System Resilience

National digital payment infrastructure can reduce reliance on external payment networks.

The Four Pillars of Stablecoin Compliance

Stablecoin compliance is increasingly becoming the foundation of institutional adoption.

While requirements vary across jurisdictions, most frameworks focus on four core pillars.

Pillar 1: Reserve Requirements

Issuers are expected to maintain sufficient liquid reserves to support redemptions.

Pillar 2: Licensing and Supervision

Regulated issuers typically operate under defined legal frameworks and supervisory oversight.

Pillar 3: Audits and Transparency

Independent verification improves confidence in reserve quality and operational controls.

Pillar 4: AML and KYC Controls

Compliance programs help prevent illicit finance risks and support integration with traditional financial systems.


Table: The Four Pillars of Stablecoin Regulation

Regulatory PillarPurpose
Reserve RequirementsMaintain redemption confidence
LicensingEnsure issuer accountability
Audits & AttestationsVerify reserve backing
AML/KYC ComplianceReduce illicit activity risk

How Regulation Drives Adoption

Stablecoin Regulation
          │
          ▼
Reserve Transparency
          │
          ▼
Market Trust
          │
          ▼
Institutional Adoption
          │
          ▼
Digital Payment Growth
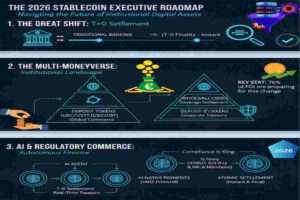
This Infographic of Stablecoin Payments 2026 Executive Roadmap shows The Great Shift from Traditional Banking to Finality Top: 'Wholesale CBDCs', Middle: 'Deposit Tokens', Base: 'Regulated Stablecoins, The Multi Money-verse of Deposit Tokens, USC/USTT & Protocol' and 'GENIUS Act & MiCA Mandates

Global Regulatory Trends in 2026

The global regulatory environment continues to evolve.

Although implementation differs by jurisdiction, several common themes are emerging.

Trend 1: Stronger Reserve Standards

Regulators increasingly favor high-quality liquid reserve assets over riskier investments.

Trend 2: Greater Disclosure Requirements

Reserve reporting and transparency expectations continue to increase.

Trend 3: Enhanced Licensing Frameworks

Digital asset service providers face stricter operational and governance requirements.

Trend 4: Focus on Cross-Border Payments

Policymakers recognize the potential efficiency gains offered by digital settlement networks.


Table: Global CBDC Development Stages

Stage Description
Research Policy analysis and feasibility studies
Pilot Programs Limited testing environments
Wholesale CBDC Bank-to-bank settlement systems
Retail CBDC Consumer-facing digital currency
Full Deployment Nationwide implementation

Infographic of Generational Wealth (2026) Explained Philosophy, Purpose Purpose & Building Legacy Beyond Money

Benefits and Risks of Digital Money

Like any financial innovation, digital money creates opportunities and challenges.

Potential Benefits

Benefit Impact
Faster Settlement Reduced payment delays
Lower Costs Reduced intermediary fees
Global Accessibility 24/7 transaction capability
Transparency Improved auditability
Programmability Automated payment logic

Key Risks

Risk Description
De-Pegging Stablecoin loses intended value
Reserve Risk Weak reserve management
Operational Risk Technology failures
Cybersecurity Risk Infrastructure attacks
Privacy Concerns Particularly relevant to CBDCs
Regulatory Risk Changing legal requirements
Infographic of Stablecoin Treasury Management 2026: Allocation Strategies, Yield Optimization & Risk Control Guide

Enterprise Use Cases and Treasury Adoption

The most significant growth in digital money may come from enterprise adoption rather than retail speculation.

Organizations increasingly evaluate stablecoins for:

  • Cross-border supplier payments
  • Treasury liquidity management
  • Global settlement operations
  • Working capital optimization
  • Real-time transfers

Treasury Evaluation Framework

Evaluation Area Importance
Reserve Transparency High
Redemption Rights High
Compliance Framework High
Custody Controls High
Audit Standards High
Regulatory Clarity High
Network Scalability Medium
Cost Efficiency Medium

Case Study: Reducing Settlement Friction

  • Challenge: An international manufacturing supplier experienced multi-day delays when paying overseas vendors through traditional banking channels.
  • Objective: Reduce settlement times while maintaining regulatory compliance.
  • Solution: The organization integrated a regulated stablecoin payment framework supported by audited reserves and institutional custody controls.
  • Result: Settlement speed improved significantly, payment visibility increased, and treasury operations became more efficient.

Case Study: The Compliance Gap

  • Challenge: A digital commerce platform adopted an unregulated payment asset without adequate compliance controls.
  • Objective: Reduce payment costs and automate global merchant payouts.
  • Outcome: The platform experienced operational disruption after regulatory scrutiny increased and counterparties restricted access to financial services.
  • Lesson: Compliance and reserve transparency remain essential components of sustainable digital money infrastructure.
This infographic of North Carolina Bitcoin Reserve 2026: From Treasury to Blockchain Explained no one talk about yet.

Future Outlook: Stablecoins and CBDCs Can Coexist

The future of digital money is unlikely to be defined by a single winner.

Instead, multiple models may coexist:

  • Stablecoins for private-sector innovation
  • CBDCs for sovereign monetary infrastructure
  • Commercial bank deposits for traditional banking
  • Tokenized assets for capital markets

The most successful systems will likely combine trust, efficiency, transparency, and regulatory clarity.

Conclusion


Conclusion — The Battle for Digital Money Control

Stablecoins and CBDCs represent two very different visions for the future of digital money. One is driven by open markets, private innovation, and global accessibility, while the other is shaped by governments, regulation, and centralized monetary control. In many ways, the debate is no longer just about technology — it is about who controls the financial infrastructure of the next generation.

Stablecoins offer speed, flexibility, borderless payments, and integration with decentralized finance, making them attractive for businesses, traders, and emerging digital economies. CBDCs, on the other hand, promise state-backed stability, regulatory oversight, and deeper integration with national financial systems. As countries accelerate their CBDC research and stablecoins continue expanding globally, the financial world may eventually operate with both systems existing side by side — sometimes cooperating, and sometimes competing directly.

Understanding this evolving landscape is essential for investors, developers, policymakers, and everyday users alike, because the outcome could redefine payments, banking, privacy, and the global balance of financial power in the years ahead.

Related Resources

To maintain topical clarity and avoid content overlap, this article should connect to a limited set of supporting authority hubs:

Each resource should address a distinct subject area while supporting a broader digital asset knowledge framework.


External Reference

18-Mar-2026 — Thus, depending on its attributes, a domestic CBDC could potentially compete with crypto (notably stablecoins), foreign CBDCs —> Read More
Digital Money FAQ

Frequently Asked Questions

Explore the relationship between stablecoins, CBDCs, digital payments, regulation and the emerging architecture of digital money in 2026.

Core Concepts

What are stablecoins?

Stablecoins are digital assets designed to maintain a relatively stable value, typically by referencing a fiat currency such as the U.S. dollar or by using reserves and other stabilization mechanisms.
Explore Stablecoin Payments →

What is a CBDC?

A Central Bank Digital Currency is a digital form of a country’s sovereign currency issued by or under the authority of its central bank. CBDCs differ from privately issued stablecoins in their issuer, legal structure and monetary-system role.
Explore Stablecoin Regulation & CBDCs →

What is the difference between stablecoins and CBDCs?

Stablecoins are generally issued by private organizations and designed around a defined stabilization mechanism, while CBDCs are sovereign digital money issued by or under the authority of a central bank. Their legal, monetary and operational structures can therefore be very different.

How Digital Money Works

How do stablecoins maintain their value?

Stablecoins can use reserve assets, redemption mechanisms, collateralization or algorithmic designs to support their target value. The exact mechanism depends on the individual stablecoin.
Explore Tokenomics Explained →

Can stablecoins replace traditional money?

Stablecoins can complement existing money and payment systems by enabling blockchain-based settlement, but their ability to replace traditional money depends on regulation, adoption, liquidity, redemption mechanisms and integration with the existing financial system.
Explore Neo-Banking & Sovereign Finance →

Why are governments developing CBDCs?

CBDC research can address goals such as payment-system modernization, settlement efficiency, financial inclusion, resilience and the continued role of central-bank money in an increasingly digital financial environment.

Risks & Regulation

Why are stablecoins regulated?

Stablecoin regulation can address issues including reserve quality, redemption, consumer protection, financial stability, disclosures, illicit-finance controls and the relationship between digital assets and the broader financial system.
Explore Stablecoin Regulations →

What are the risks of stablecoins?

Key risks can include loss of the intended peg, reserve or counterparty risk, liquidity constraints, operational failures, smart-contract vulnerabilities and regulatory uncertainty. Risk varies substantially between stablecoin designs.

Are CBDCs safe to use?

CBDC safety depends on the technical, legal and institutional design of the system. Important considerations can include cybersecurity, privacy protections, identity architecture, operational resilience, access controls and the role of the central bank.
Explore Financial Sovereignty →

Future of Digital Money

Will stablecoins and CBDCs coexist?

They can coexist because they serve different institutional and economic roles. Stablecoins are privately issued digital assets, while CBDCs represent digital sovereign money. Their future relationship will depend on regulation, adoption and payment-system integration.

How will digital money change global payments?

Digital money can enable faster settlement, programmable payments, new cross-border payment models and blockchain-based financial infrastructure. The practical impact will depend on interoperability, regulation, liquidity and adoption.
Explore Stablecoin Payments 2026 →

What is the future of digital money?

Digital money is likely to develop through a combination of stablecoins, central-bank digital money, tokenized assets, traditional banking infrastructure and blockchain-based settlement. The resulting system may be more interconnected rather than simply replacing one form of money with another.
Looking for another topic? Search the OwnProCrypto research archive.
Comments
💬 What’s Your Take? Leave a Comment Below 0
← Digital Asset Taxation Hub: Crypto Tax Rules & Compliance Guide (2026)
MiCA & GENIUS Act Roadmap – Crypto Compliance 2026 Experts Guide →
🛠 Explore Tools ▼
📚 Explore Crypto Research Select a research category