
Search by title, topic or phrase
Use our Crypto Search Engine 🔍 to find the topics and keywords you're looking for.
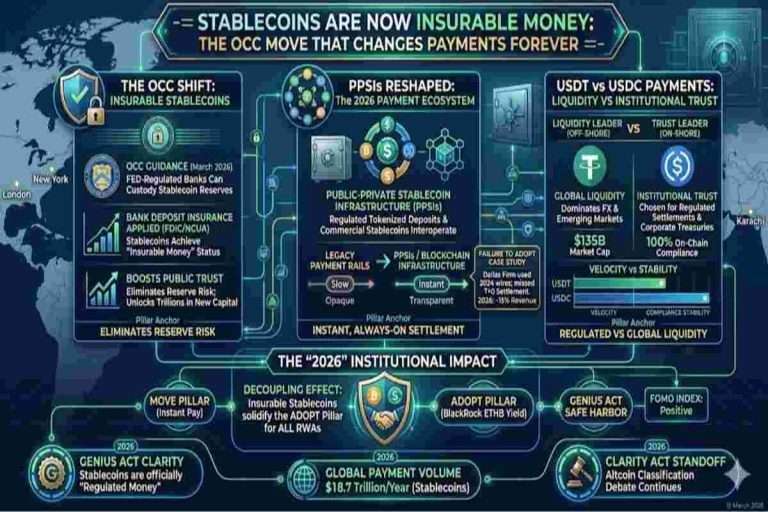
Table of Contents
ToggleStablecoins were originally viewed as a bridge between traditional finance and cryptocurrency, but growing regulation and stronger reserve requirements are changing how they are perceived, leading many to ask: Stablecoins Are Now Insurable Money? Today, many major stablecoin issuers hold reserves in cash and short-term government securities, while regulators are introducing rules focused on transparency, audits, and consumer protection. Although stablecoins are not the same as bank deposits and may not carry traditional deposit insurance, some are increasingly being backed by regulated reserve structures designed to improve security and trust. Understanding how reserve protection and regulation work can help users evaluate the safety of different stablecoins and their role in the future of digital payments.
This development raises an important question:
stablecoins Are Now Insurable Money ?
While the answer remains nuanced, the underlying trend is clear. Enterprise adoption is increasingly driven by trust architecture rather than blockchain technology alone. It means stablecoins can be treated as regulated financial instruments with potential insurance protections that make them viable for institutional use.
The conversation around stablecoins has changed dramatically over the past several years.
Early adoption was driven largely by trading activity and cryptocurrency market liquidity. Today, many organizations are evaluating stablecoins for settlement, treasury operations, cross-border payments, and liquidity management.
The shift reflects a broader change in how digital dollars are perceived.
| Era | Primary Trust Mechanism | Key Risk |
|---|---|---|
| Physical Cash | Sovereign backing | Theft and loss |
| Bank Deposits | Banking regulation and deposit protection | Bank failure |
| Electronic Payments | Financial infrastructure networks | Settlement delays |
| Early Stablecoins | Issuer credibility | Reserve uncertainty |
| Modern Stablecoins | Reserves, regulation, audits, and controls | Operational and custody risk |
Physical Cash
      │
      ▼
Commercial Bank Deposits
      │
      ▼
Electronic Payment Networks
      │
      ▼
Stablecoins
      │
      ▼
Reserve Protection
Custody Controls
Independent Audits
Regulatory Oversight
Insurance Coverage
      │
      ▼
Emerging "Insurable Money"The term “insurable money” does not refer to a formal legal classification.
Instead, it describes an emerging framework where digital dollar assets are supported by multiple layers of protection that make them more suitable for enterprise use.
These protections may include:
The concept is not that stablecoins become identical to bank deposits.
The concept is that stablecoins become sufficiently protected and auditable to fit within institutional risk-management frameworks.
Most discussions focus only on reserve backing.
In practice, institutional trust depends on several layers working together.
Stablecoins typically maintain reserves designed to support redemption requests.
Examples may include:
Institutional users increasingly expect customer assets and reserve assets to remain separated from issuer operating capital.
This structure reduces exposure to corporate insolvency risks.
Verification mechanisms may include:
These tools improve transparency and market confidence.
Regulatory frameworks continue to evolve globally.
Common requirements increasingly focus on:
Insurance products are becoming an increasingly important component of institutional adoption.
Coverage may include:
┌──────────────────────────┐
│ Insurance Coverage       │
└─────────────┬────────────┘
              ▼
┌──────────────────────────┐
│ Regulatory Oversight     │
└─────────────┬────────────┘
              ▼
┌──────────────────────────┐
│ Independent Verification │
└─────────────┬────────────┘
              ▼
┌──────────────────────────┐
│ Segregated Custody       │
└─────────────┬────────────┘
              ▼
┌──────────────────────────┐
│ Reserve Assets           │
└──────────────────────────┘
Regulation is increasingly viewed as an adoption catalyst rather than an obstacle.
For institutional participants, legal certainty often matters more than technological innovation.
Clear regulatory standards help organizations evaluate:
This reduces uncertainty and improves confidence in deployment decisions.
| Evaluation Area | Importance |
| Reserve transparency | High |
| Redemption rights | High |
| Custody controls | High |
| Regulatory clarity | High |
| Audit standards | High |
| Insurance coverage | Medium to High |
| Blockchain network selection | Medium |
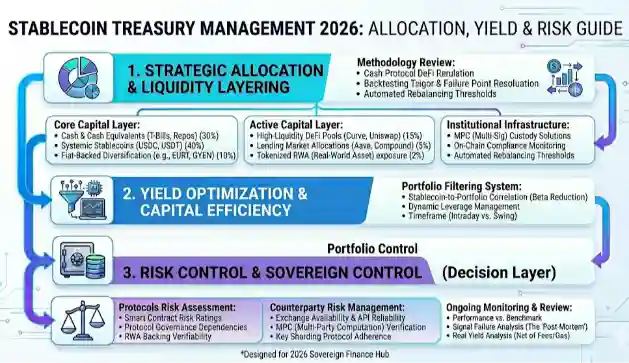
Treasury teams increasingly evaluate stablecoins as operational tools rather than speculative assets.
Potential use cases include:
The primary value proposition is often speed, visibility, and capital efficiency.
| Treasury Objective | Potential Benefit |
| Global liquidity management | Near real-time transfers |
| Cash visibility | Transparent transaction records |
| Working capital optimization | Reduced settlement delays |
| Vendor settlement | Faster payment execution |
| Risk management | Enhanced reserve transparency |
| Audit readiness | Verifiable transaction history |
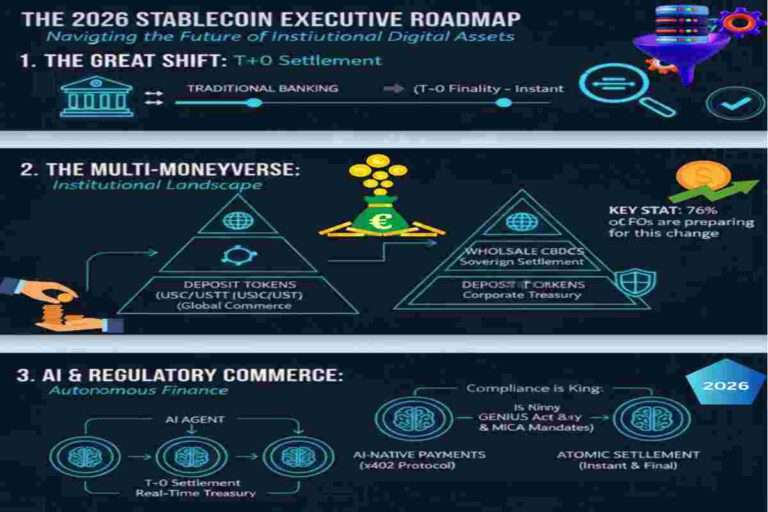
Traditional Model

Company
   │
   ▼
Bank
   │
   ▼
Payment Processor
   │
   ▼
Settlement Network
   │
   ▼
Recipient

Settlement Time: Hours to Days
────────────────────────

Stablecoin Model

Company Wallet
      │
      ▼
Stablecoin Network
      │
      ▼
Recipient Wallet

Settlement Time: Minutes or LessDifferent stablecoins often serve different market needs.
| Feature | USDT | USDC |
| Global liquidity | Very High | High |
| Exchange presence | Very High | High |
| Institutional adoption | Moderate | High |
| Transparency focus | Moderate | High |
| Regulatory alignment | Moderate | Higher |
| Treasury suitability | Medium | High |
The choice depends on use case, jurisdiction, risk tolerance, and operational requirements.
The future of enterprise stablecoin adoption may depend less on blockchain innovation and more on trust infrastructure.
Stablecoin
      │
      ▼
Reserve Backing
      │
      ▼
Segregated Custody
      │
      ▼
Independent Verification
      │
      ▼
Regulatory Oversight
      │
      ▼
Insurance Protection
      │
      ▼
Enterprise Confidence
      │
      ▼
Insurable Money
This framework provides a practical way to evaluate whether a stablecoin is suitable for treasury, payments, or institutional settlement use cases.
1:1 backed stablecoins are digital assets designed to maintain a fixed value by holding an equivalent reserve for every token issued. In practice, this means each stablecoin is supported by real-world assets such as cash or short-term government securities, ensuring redeemability at par value. Regulators, including the Office of the Comptroller of the Currency, increasingly emphasize this reserve model as a foundation for financial stability. For widely used assets like USD Coin, strict 1:1 backing combined with transparency and audits is what enables their evolution toward being treated as reliable, cash-like instruments in the digital economy.
A global professional services firm integrated regulated USDC rails into its treasury operations to settle cross‑border transactions. By leveraging PPSI‑compliant stablecoin infrastructure and securing insurance coverage against operational risk, it reduced settlement costs by 60% and improved global cash flow visibility — demonstrating how Stablecoins Are Now Insurable Money in practice.
Stablecoins are undergoing a profound transformation. No longer confined to speculative trading, they are becoming regulated, institutionally adopted, and insurable money capable of supporting the future of payments. The industry is recognizing that Stablecoins Are Now Insurable Money. Consequently, compliant stablecoins like USDC are positioned at the forefront of financial innovation, while digital liquidity solution like USDT continue to serve core global value flows.
As we enter 2026, the convergence of the GENIUS Act and institutional custody solutions has solidified a new financial reality: Stablecoins Are Now Insurable Money. This shift marks the end of the experimental era, providing the regulatory “Safe Harbor” and capital protections required for state treasuries and global enterprises to deploy stablecoin rails with the same fiduciary confidence as traditional fiat.
This intersection — compliance, infrastructure, and insurance — defines not just winners in the stablecoin market but the next generation of financial rails.
To maintain topical clarity and avoid content overlap, this article should connect to a limited set of supporting authority hubs:
Each resource should address a distinct subject area while supporting a broader digital asset knowledge framework.
For those conducting deep-dive due diligence on the GENIUS Act compliance requirements, you can access the latest federal rulemaking and “Permitted Activity” bulletins directly via the official government portal at http://occ.treas.gov/topics/supervision-and-examination/digital-assets. This transparency is the “Gold Standard” for institutional MOVE operations in 2026.
[Legacy Bank Rails] ──(Multi-day Delay)──➔ [Intermediary Fees] ──➔ [Settlement Window]
[Regulated Crypto Rails] ──(Instant T+0 Cleared)──➔ [Audited Reserves] ──➔ [Insurable Balance]
Q: What does “Stablecoins Are Now Insurable Money” mean?
It means stablecoins can be treated as regulated financial instruments with potential insurance protections that make them viable for institutional use.
Q: Why does stablecoin regulation in 2026 matter?
It provides legal clarity and compliance standards that encourage institutional integration and merchant acceptance.
Q: Why is the yield ban significant?
Stablecoins cannot pay interest or yield, reinforcing their role as pure payment instruments rather than investment products.
Q: What’s the difference between USDT and USDC in payments?
USDT leads in liquidity and market activity, while USDC is often preferred in regulated institution payment contexts.
Q: Are all stablecoins eligible for insurance?
Insurance depends on regulatory compliance, custodian safeguards, and risk underwriting — not all stablecoins qualify equally.
Q: How do stablecoin insurance products work?
They cover technological, custodial, and operational risks that traditional protections like FDIC do not. Insurance is a newer development in stablecoin adoption.
Q: Can traditional banks issue stablecoins?
Yes — banks and chartered entities can issue compliant stablecoins through PPSI frameworks.
Q: What does this mean for global payments?
It signals an evolution in financial infrastructure where stablecoin rails coexist with regulated payment systems, offering speed, transparency, and risk‑managed settlement.
Q: What exactly is a PPSI under the 2026 OCC proposal?
A PPSI (Permitted Payment Stablecoin Issuer) is a federally regulated entity authorized by the OCC to issue digital cash. To qualify, an issuer must maintain 1:1 liquid reserves and undergo monthly federal audits.
Case Study Failure: In 2023, a major stablecoin de-pegged because its reserves were tied up in a single, failing regional bank. The Fix: The OCC’s PPSI rules now mandate diversified treasury holdings across multiple insured institutions to prevent “Single Point of Failure” liquidity traps.
Q: Why does the GENIUS Act prohibit stablecoins from paying interest?
By stripping yield, the Act ensures stablecoins are classified as Currency rather than Securities. This allows corporations to use them for settlement without triggering SEC “Investment Contract” audits.
Case Study Failure: A Dallas fintech tried to offer 5% “Real Yield” on its payment token in 2025. The SEC froze the protocol’s move-rails, citing an unregistered securities offering. The Fix: Stick to yield-free PPSI tokens for 100% legal uptime.
Q: Why did Aon use both Ethereum and Solana for their March 2026 settlement?
This is called Multi-Rail Resiliency. Ethereum (USDC) provides deep, institutional-grade security for large tranches, while Solana (PYUSD) offers the sub-second finality needed for high-frequency treasury adjustments.
Case Study Failure: A mid-sized broker moved all operations to a single “Private Chain” in 2024. When the chain’s sole validator crashed, they couldn’t settle premiums for 72 hours. The Fix: Use a “Chain Agnostic” model like Aon to ensure 24/7 global liquidity.
Q: How does the “Swift + Thunes” integration affect global payments?
It bridges the 11,500 Swift-connected banks directly to on-chain wallets. A CEO can now initiate a Swift message in London that settles as USDC in a Singapore wallet in seconds.
Case Study Failure: Before the 2026 Thunes bridge, firms had to use shady “Off-Ramp” providers that charged 3% fees and took 48 hours to clear. The Fix: Use the Swift-integrated PPSI rails for near-zero friction.
Q: Can we insure the “Move” against smart contract failure?
Yes. 2026 Cyber Insurance products, like those pioneered by Aon, now include “Logic Hack” coverage. This protects the sender if a protocol bridge or escrow contract is exploited during the settlement window.
Case Study Failure: An early adopter lost $2M in 2024 during a bridge exploit. Their traditional insurance denied the claim because “digital assets” weren’t explicitly covered. The Fix: Ensure your policy specifically lists On-Chain Settlement Logic under covered assets.
Q: Is “Self-Custody” too risky for a $73B corporation?
Not with MPC (Multi-Party Computation) and Institutional Custody. Firms no longer use “Private Keys” on a single laptop; they use distributed shards that require multiple executive approvals.
Case Study Failure: A CEO lost access to $10M in 2023 because he was the only person with the seed phrase. The Fix: Implement MPC-based Governance so no single person—or hack—can move funds without a multi-sig consensus.
Q: How does the $74K Bitcoin breakout affect the MOVE pillar?
While Bitcoin is an OWN asset, its price stability (or “Breakout”) increases the total liquidity of the ecosystem, making it cheaper and easier for institutions to swap into stablecoins for settlement.
Case Study Failure: During the “Crypto Winter” of 2022, low liquidity meant that moving $50M caused 2% “Slippage.” The Fix: In the $74K+ market of 2026, deep institutional liquidity ensures “Move” costs stay under 0.01%.
Q: Does the “20 Millionth Bitcoin” milestone change treasury strategy?
Absolutely. With 95% of supply now issued, Bitcoin has transitioned from a “Tech Bet” to a Sovereign Treasury Reserve. It is now the “Hard Anchor” for the entire digital financial stack.
Case Study Failure: Corporations that waited for “21 million” to be mined found themselves priced out. The Fix: Forward-thinking CEOs are stacking BTC now as a hedge against the fiat-elasticity of the legacy system.
Q: What is the “Web3 Architecture Map” mentioned in the intro?
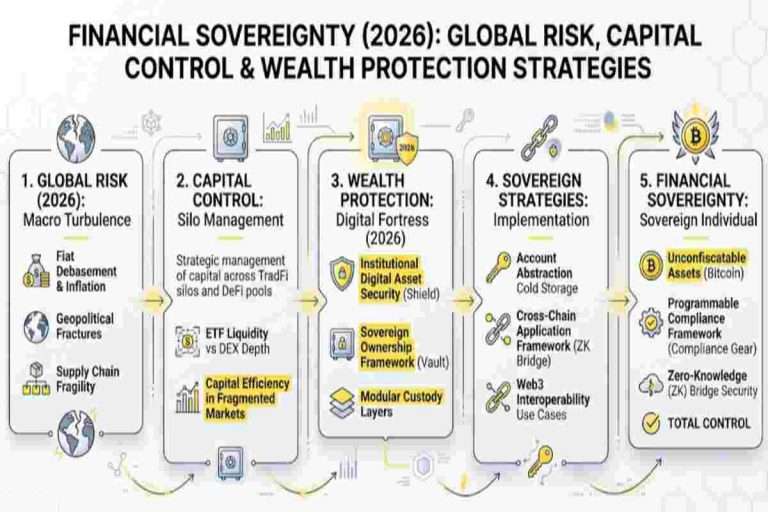
It is a professional-grade strategic template designed for institutional portfolio architecture, ensuring On-Chain Compliance and wealth preservation.
Case Study Failure: A builder tried to scale without a map in 2024 and ended up with “Fragmented Liquidity” across 12 different chains, doubling their operational costs. The Fix: Use the Architecture Map to consolidate your “Move” rails from Day.
Q: Will CBDCs replace PPSI Stablecoins?
Unlikely in 2026. While CBDCs are coming, PPSIs (like USDC) provide the “Programmable Logic” and multi-chain interoperability that rigid government-led coins currently lack.
Case Study Failure: A firm banked on a specific 2025 CBDC pilot that never went live, wasting $1M in dev costs. The Fix: Build on PPSI rails today; they are already live, liquid, and federally recognized under the GENIUS Act.